
- Do not charge domestic VAT and do not cite intra-EU Article 196 or VIES.
- Under Article 44 of Directive 2006/112/EC (§ 3a Abs. 2 UStG in DE, Art. 259-1° CGI in FR, Art. 69 LIVA in ES), the place of supply shifts to the buyer's country, making the invoice outside the scope of EU VAT.
- For Swiss clients, verify their UID number (`CHE-xxx.xxx.xxx MWST`) on uid.admin.ch. The Swiss client self-accounts for 8.1% Swiss acquisition tax (*Bezugssteuer*).
- Report the net revenue in your domestic VAT return's non-taxable foreign services box (e.g., Field 45 in Germany, Casilla 120 in Spain, Line E2 in France) and never on your EC Sales List (ZM, Modelo 349, DES, or ICP).
1. Why Intra-EU Article 196 Does Not Apply to Switzerland, the UK, or the US
One of the most frequent search queries among European freelancers is "USt-IdNr. Schweiz Reverse Charge" or "Does Article 196 apply to Switzerland and the UK?". In everyday conversation, clients and accountants often refer to Swiss or UK B2B invoices as "reverse charge" because the outcome looks identical on the surface: you issue a net invoice without VAT, and the corporate buyer handles the tax in their own jurisdiction.
Legally and in your tax filings, however, intra-EU reverse charge (Article 196) and third-country B2B supplies (Article 44) follow two completely separate tracks. Mixing them up causes immediate mismatches between your VAT return and your EC Sales List.
| Requirement | Intra-EU B2B (e.g., Client in DE, FR, NL, IE) | Non-EU / Third Country B2B (Switzerland, UK, US) |
|---|---|---|
| EU Legal Basis | Art. 44 + Art. 196 Directive 2006/112/EC | Art. 44 Directive 2006/112/EC (Place of supply outside EU) |
| National Law Reference | DE: § 13b UStG · FR: Art. 283-2 CGI · ES: Art. 84 LIVA | DE: § 3a Abs. 2 UStG · FR: Art. 259-1° CGI · ES: Art. 69.Uno.1º LIVA |
| Tax Status of Supply | Intra-Community B2B Reverse Charge | Outside the scope of EU VAT (*Nicht im Inland steuerbar*) |
| Buyer Tax ID Verification | Mandatory EU VIES validation | Not in VIES. Verify Swiss UID (`CHE-...`), UK VAT/Companies House, or US EIN / W-8BEN-E |
| Domestic VAT Return Box | DE: Field 21 · ES: Casilla 59 · NL: Rubriek 3b | DE: Field 45 · ES: Casilla 120 · FR: Ligne E2 · NL: Omit from 3b |
| EC Sales List (ZM / 349 / DES / ICP) | Mandatory filing (penalties if omitted) | Do NOT report (system will reject non-EU country codes) |
2. Interactive Non-EU & Switzerland Invoice Clause Generator
Select your EU country of establishment and your client's country below to generate the exact statutory invoice wording, domestic VAT return box, and proof-of-business checklist:
Mandatory Invoice Remark (Copy & Paste):
Nicht im Inland steuerbare sonstige Leistung gemäß § 3a Abs. 2 UStG (Place of supply is Switzerland under Art. 44 of Directive 2006/112/EC; subject to Swiss Bezugssteuer under Art. 45 MWSTG).
Your Statutory Filing & Proof Checklist:
- German USt-Voranmeldung: Report net amount in Kennziffer 45 (Übrige nicht steuerbare Umsätze, Leistungsort nicht im Inland) - do NOT use Kennziffer 21.
- Zusammenfassende Meldung (ZM): Do not include in your ZM filing (Switzerland is outside the EU).
- Swiss Buyer Proof: Record the client's Swiss UID (e.g.,
CHE-123.456.789 MWST) and archive a verification screenshot fromuid.admin.ch.
Want a ready-to-use Cross-Border Invoice Template & VAT Reserve Sheet?
Download the free SoloTreasury Lite Starter Kit (ZIP) - includes our cross-border invoice checklist, ECB exchange rate guide, and the Lite Tax Reserve Calculator for DE, ES, FR, NL & CY.
Instant ZIP download + email copy. Zero spam. Unsubscribe anytime.
3. Swiss UID Number (CHE-xxx.xxx.xxx MWST), Bezugssteuer & the CHF 100,000 Rule
Switzerland is integrated into the European single market in many practical ways, which is why EU freelancers are often surprised when a Swiss VAT number fails in the EU VIES validator. Here are the three Swiss VAT rules every EU freelancer must know:
1. How to Verify a Swiss Business Client (UID-Register)
Since 2014, Switzerland uses a uniform enterprise identification number called the UID (*Unternehmens-Identifikationsnummer*). It always follows this format:
- German cantons (e.g., Zurich, Basel, Bern, Zug):
CHE-123.456.789 MWST - French cantons (e.g., Geneva, Vaud):
CHE-123.456.789 TVA - Italian canton (Ticino):
CHE-123.456.789 IVA
Because Switzerland is not part of the EU VIES system, you validate this number on the official Swiss Federal Statistical Office portal at uid.admin.ch. Print or save the confirmation showing that the entity is active in the commercial register (*Handelsregister*) or VAT register. Even if a small Swiss startup is not registered for Swiss VAT (because its turnover is under CHF 100,000), an active UID entry proves its B2B entrepreneurial status under Article 44.
2. What Happens on the Swiss Side: Bezugssteuer (Art. 45 MWSTG)
Under Article 45 of the Swiss Value Added Tax Act (MWSTG), when a Swiss company purchases consulting, software development, design, marketing, or management services from an EU freelancer established outside Switzerland, the Swiss recipient is subject to Bezugssteuer (Acquisition Tax / *Impôt sur les acquisitions*).
- The Swiss client self-assesses the standard 8.1% Swiss VAT on your net invoice amount in their own Swiss VAT return.
- If the Swiss client is fully entitled to input tax deduction (*Vorsteuerabzug*), they deduct the 8.1% in the exact same return, resulting in zero net tax cost.
- If the Swiss buyer is not registered for Swiss VAT, they only become liable to pay Bezugssteuer if they import more than CHF 10,000 of foreign services per calendar year. Either way, that obligation rests strictly on the Swiss buyer, never on you as the EU service provider.
3. Do You Need to Register for Swiss VAT Over CHF 100,000? (The Art. 10 MWSTG Exception)
You may have heard a frightening rule introduced in 2018: foreign businesses with CHF 100,000 or more in worldwide annual turnover become liable for Swiss VAT from their very first franc of revenue in Switzerland. Many EU freelancers earning €95,000+ globally panic and wonder if taking on one Swiss client forces them to appoint a Swiss fiscal representative.
When DOES the CHF 100,000 rule force Swiss VAT registration? Only in two specific scenarios:
- B2C Digital & Telecom Services to Swiss Consumers: If you sell automated SaaS subscriptions, e-books, or online courses to non-business private individuals in Switzerland and your global turnover exceeds CHF 100,000.
- Work on Physical Goods or Real Estate in Switzerland (*Werkvertragliche Lieferungen*): If you travel to Switzerland to install hardware, perform physical construction/assembly, or provide services directly tied to Swiss real estate.
4. Copy-Paste Invoice Wording for Switzerland, the UK & the US
When invoicing a business client in Switzerland, the UK, or the US, do not cite Article 196. Instead, include the statutory reference for services supplied outside the scope of EU VAT under Article 44:
Service outside the scope of EU VAT - place of supply is the recipient's country in accordance with Article 44 of Council Directive 2006/112/EC (Recipient to account for any applicable local acquisition tax / reverse charge).
Nicht im Inland steuerbare sonstige Leistung gemäß § 3a Abs. 2 UStG (Leistungsort liegt im Drittland / Schweiz; Bezugssteuer durch den Leistungsempfänger).
TVA non applicable - prestation de services située hors de l'Union européenne conformément à l'article 259-1° du CGI et à l'article 44 de la Directive 2006/112/CE.
Operación no sujeta al IVA por reglas de localización conforme al artículo 69.Uno.1º de la Ley 37/1992 del IVA (Art. 44 Directiva 2006/112/CE).
Dienst buiten de EU - niet belast voor de Nederlandse btw op grond van artikel 6, lid 1 Wet op de omzetbelasting 1968 (Art. 44 Richtlijn 2006/112/EG).
5. How to Report Switzerland & Non-EU Invoices on Your Domestic VAT Return
Even though no VAT is charged on a non-EU B2B invoice, EU tax authorities require you to declare the net revenue in the specific box for non-taxable supplies where the place of supply is outside the domestic territory. Crucially, you must keep these separate from your intra-EU reverse-charge box so your VAT return matches your EC Sales List:
| Your EU Country | Domestic VAT Return Box (CH / UK / US Clients) | Intra-EU Box to Avoid | EC Sales List Rule |
|---|---|---|---|
| 🇩🇪 Germany (USt-VA) | Kennziffer 45 (Übrige nicht steuerbare Umsätze, Leistungsort nicht im Inland) | Do NOT put in Kennziffer 21 (strictly for EU § 13b) | Omit from ZM (BZSt) |
| 🇪🇸 Spain (Modelo 303) | Casilla 120 (Operaciones no sujetas por reglas de localización) | Do NOT put in Casilla 59 (strictly for intra-EU) | Omit from Modelo 349 |
| 🇫🇷 France (Déclaration CA3) | Ligne E2 (Autres opérations non imposables) | Separate from intra-EU service tracking | Omit from DES (Douanes) |
| 🇳🇱 Netherlands (BTW-aangifte) | Omit from Rubriek 3b (record in administration for income tax / turnover reconciliation) | Do NOT put in Rubriek 3b (strictly intra-EU) | Omit from ICP (Opgaaf ICP) |
6. Worked Example: Invoicing a Swiss Client in CHF or EUR (Plus FX Conversion)
Suppose you are a freelance software architect based in Berlin, Germany, and you complete a CHF 5,000 (or €5,200) milestone for a fintech client in Zurich, Switzerland (AlpenTech AG, UID: CHE-116.281.490 MWST):
Lukas Weber · IT Architecture
Torstraße 112, 10119 Berlin, Germany
Steuernummer: 34/567/89012
USt-IdNr.: DE 123 456 789
AlpenTech AG
Bahnhofstrasse 42, 8001 Zürich, Switzerland
Swiss UID: CHE-116.281.490 MWST
(Verified on uid.admin.ch on 2026-10-13)
Description: Cloud Infrastructure & Security Audit (80 hrs @ €65.00/hr)
VAT (0% - Outside scope of EU VAT): €0.00
Total Payable: €5,200.00
Nicht im Inland steuerbare sonstige Leistung gemäß § 3a Abs. 2 UStG. Service outside the scope of EU VAT in accordance with Article 44 of Council Directive 2006/112/EC (Recipient liable for Swiss Bezugssteuer under Art. 45 MWSTG).
What If You Invoice in CHF, USD, or GBP?
Clients in Zurich, London, and San Francisco frequently ask to be billed in CHF, GBP, or USD. When you issue a foreign-currency invoice from a Eurozone country:
- Cash-basis income tax (EÜR in DE / IRPF in ES / Micro-BNC in FR): You must convert the foreign currency payment into EUR using the exchange rate on the day the money hits your business bank account (or the official European Central Bank (ECB) daily reference rate on the payment date), and record any Wise/Revolut currency conversion fee as a deductible business expense.
- VAT return reporting: Even though €0.00 VAT is due, the net amount reported in Field 45 (Germany) or Casilla 120 (Spain) must be stated in EUR using the official ECB or Ministry of Finance monthly/daily exchange rate.
Track CHF, USD, GBP & EUR Invoices in One Sovereign Google Sheet
SoloTreasury is a Google Sheets treasury cockpit built for EU freelancers in DE, ES, FR, NL, and CY. Log invoices in EUR, USD, GBP, or CHF - the sheet fetches the official ECB exchange rate for your payment date, separates domestic VAT from non-EU and Article 196 revenue, and shows your true Net Spendable Cash after income tax reserves.
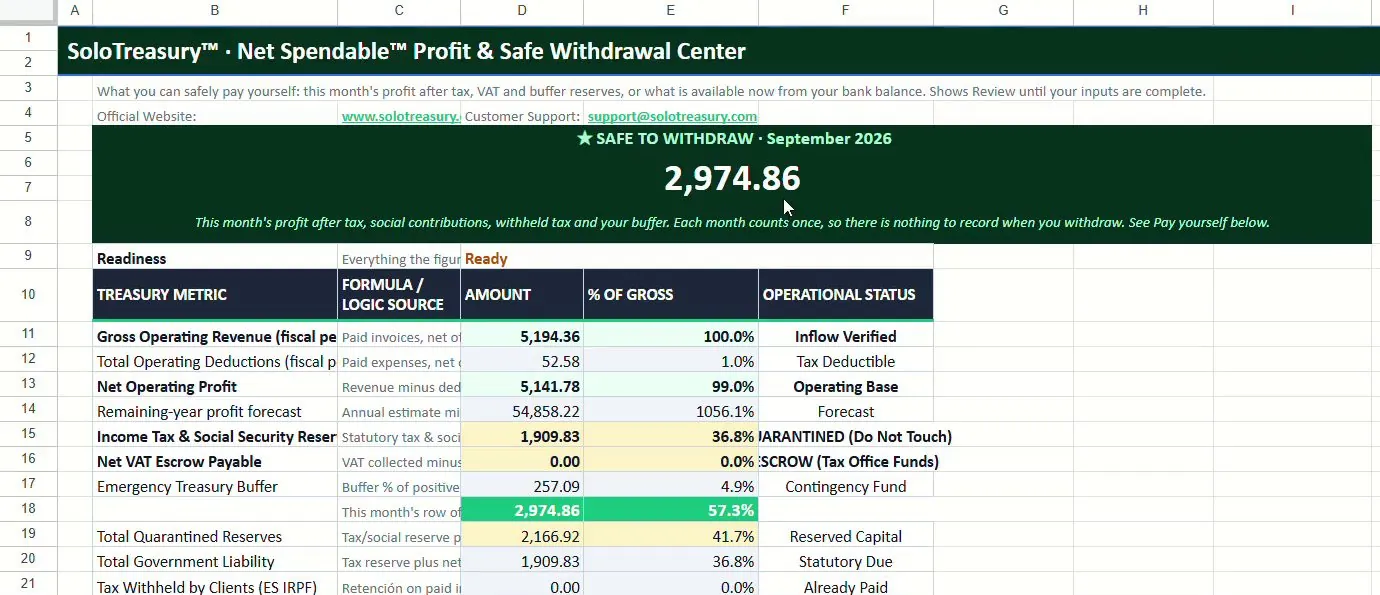 Live Google Sheet · Multi-Currency ECB Rates · One-time €49
7. Frequently Asked Questions
Does EU Article 196 Reverse Charge apply when invoicing a client in Switzerland?
No. Article 196 of Council Directive 2006/112/EC applies strictly to intra-Community B2B supplies between two EU Member States. Because Switzerland is outside the EU VAT territory, B2B services supplied to a Swiss business fall under the general place-of-supply rule in Article 44 (§ 3a Abs. 2 UStG in Germany, Art. 259-1° CGI in France, Art. 69 LIVA in Spain). The service is outside the scope of EU VAT, and the Swiss buyer accounts for Swiss acquisition tax (Bezugssteuer) under Art. 45 MWSTG.
How do I verify a Swiss client's VAT number if Switzerland is not in VIES?
Swiss businesses are not listed in the EU VIES database. Instead, a Swiss business uses a UID number in the format CHE-123.456.789 MWST (or TVA / IVA). You verify this number free of charge on the official Swiss Federal Statistical Office UID-Register (uid.admin.ch) and save the PDF or screenshot as proof of your client's entrepreneurial status.
Do I need to register for Swiss VAT if my worldwide turnover exceeds CHF 100,000?
Not if you only supply standard B2B services (such as software development, consulting, design, or marketing) that are subject to Swiss acquisition tax (Bezugssteuer) by the Swiss business recipient. Under Article 10(2)(b) of the Swiss VAT Act (MWSTG), foreign businesses providing exclusively services subject to Bezugssteuer are exempt from mandatory Swiss VAT registration regardless of whether their global turnover exceeds CHF 100,000. Registration is triggered if you supply B2C digital/telecom services to Swiss private consumers or perform physical work on goods/real estate in Switzerland.
Do I report invoices to Switzerland, the UK, or the US on my EC Sales List (ZM / Modelo 349 / DES)?
No. EC Sales Lists (Zusammenfassende Meldung in Germany, Modelo 349 in Spain, DES in France, ICP in the Netherlands) are exclusively for intra-EU B2B transactions. Invoices to Switzerland, the UK, and the US must never be included in an EC Sales List; instead, report them in the designated box for non-taxable foreign services on your domestic VAT return (e.g., Kennziffer 45 in Germany, Casilla 120 in Spain, Ligne E2 in France).
What wording must appear on an invoice to a Swiss, UK, or US business client?
Your invoice should state that the supply is outside the scope of domestic EU VAT because the place of supply is where the business recipient is established: "Service outside the scope of EU VAT - place of supply is the recipient's country under Article 44 of Directive 2006/112/EC" (in Germany: "Nicht im Inland steuerbare Leistung gemäß § 3a Abs. 2 UStG"; in France: "TVA non applicable - art. 259-1° du CGI"; in Spain: "Operación no sujeta por reglas de localización - art. 69 LIVA").
What about Liechtenstein, Norway, or the United Kingdom?
Liechtenstein is part of the Swiss VAT territory and uses the same UID system and Bezugssteuer rules as Switzerland. Norway and the United Kingdom are also third countries outside the EU VAT area (with the exception of Northern Ireland for physical goods, not services). For B2B services to UK or Norwegian companies, the same Article 44 outside-scope rule applies: charge €0.00 EU VAT, archive proof of the buyer's business status (UK VAT number or Companies House registration), and omit from your EC Sales List.
9. Official Sources & Legal Citations
Verified October 2026. This guide provides general statutory reference information for financial planning and does not constitute tax or legal advice.
- Council Directive 2006/112/EC (Article 44 Place of Supply of Services)
- Swiss Federal Act on Value Added Tax (MWSTG) - Art. 10 (Registration Exemption) & Art. 45 (Bezugssteuer)
- Swiss Federal Statistical Office: Official UID-Register (uid.admin.ch)
- German VAT Act: § 3a Abs. 2 UStG (Ort der sonstigen Leistung)
- Spanish VAT Act: Ley 37/1992 (LIVA), Artículo 69 (Reglas de localización)
- French General Tax Code: Article 259-1° du CGI